

Field note
Backyard Upgrade Financing: Turf, Pergolas, and 0% APR
How backyard upgrade financing works for artificial turf and pergolas, what 0% APR really means, and the questions to ask before you sign.
2026-11-20 · 7 min read
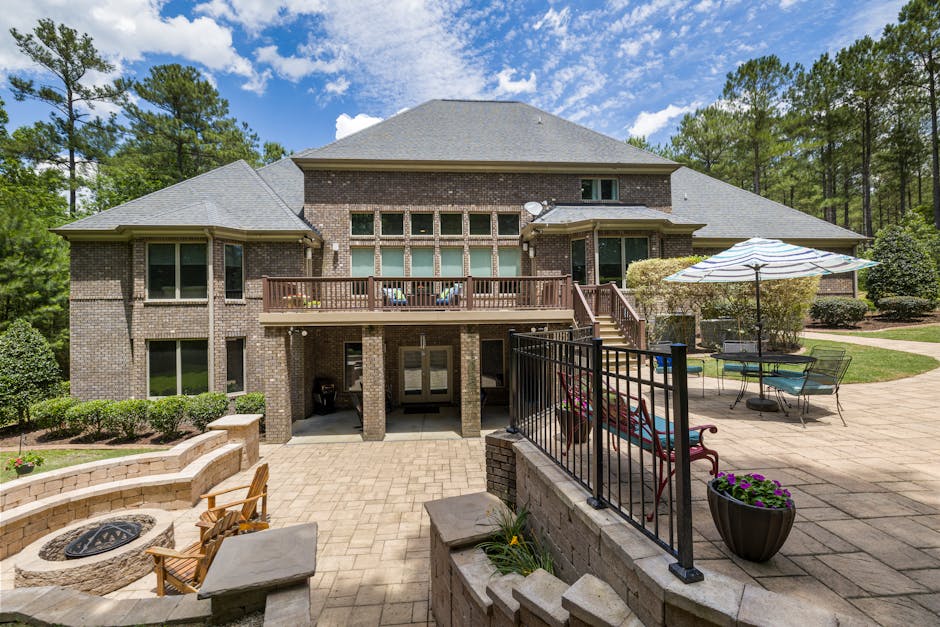
A backyard upgrade rarely shows up as one clean line on a budget. There is the turf, the base and drainage work underneath it, the pergola that turns a patch of grass into a room, and the small extras that only surface after demo. Add it all up and a project that started as "let's fix the dead grass" turns into a five-figure decision. That gap between what you want and what you have sitting in savings is where backyard upgrade financing earns its place.
DFW Turf Pros offers 0% APR financing alongside its turf installation and pergola projects, and the details behind that headline number matter more than the number itself. Here is what to understand before you sign anything.
Why Backyard Projects Get Priced in Pieces
Most homeowners start with one item and end up with four. A typical DFW backyard renovation touches several distinct scopes of work:
- Removal of existing grass, gravel, or concrete
- Base excavation and compaction, the part nobody sees and everybody underprices
- Drainage corrections, especially on the heavy clay soil common across North Texas
- Artificial turf material, infill, and installation
- Pergola design, materials, and anchoring
Financing the whole scope in one application is usually simpler than stitching together separate loans or credit card balances as each piece gets done. It also lets the installer sequence the work correctly instead of forcing a pergola crew to work around turf that went in too early.
What 0% APR Actually Means on a Backyard Project
A 0% APR offer means no interest is charged on the financed balance, but the terms attached to that number do the real work. Two offers with identical 0% headlines can behave very differently once a payment is missed or the promotional window closes.
Ask whether the interest is waived or deferred
Waived interest disappears. Deferred interest can come back if the balance is not cleared inside the promotional period, and sometimes it returns as a lump sum calculated from the original purchase date. The difference between those two structures is worth a direct question during the estimate, not a guess after the paperwork arrives.
Know the length of the promotional window
Published industry guidance on landscape financing describes short interest-free windows, in some cases around six months, on projects above a minimum size. Shorter windows mean higher monthly payments if your goal is to clear the balance before interest kicks in. Match the term to a payment you can sustain, not to the longest window a lender is willing to offer.
Check what happens after the promo ends
Any balance left when the 0% period closes typically rolls into a standard rate. Ask what that rate is, ask whether it is fixed or variable, and ask for the total cost of the loan assuming you pay the minimum every month. That figure is the honest price of the project, and it is rarely printed on the flyer.

Turf and Pergola Are Not the Same Purchase
Both can sit on one financing application, but they carry different cost drivers and different questions. DFW Turf Pros installs pergolas through its Sola Outdoor partnership, which means the structure side of the estimate comes from a different set of decisions than the turf side.
| Project | Where the money goes | What to confirm |
|---|---|---|
| Artificial turf | Excavation, base, drainage, turf material, infill, labor | Base depth, drainage plan, warranty length, annual maintenance terms |
| Pergola | Structure, materials, anchoring, installation | Who handles any required approvals, anchoring method, exposure to wind |
Turf is largely a groundwork purchase. The visible product goes in last and is the cheapest thing to get wrong. A pergola is a structure purchase, so material choice and anchoring carry most of the risk. Financing both at once is reasonable, but it helps to know which half of the invoice is engineering and which half is material.
Bundling Turf and a Pergola Into One Project
Combining the two is often the smarter financial move, not just the convenient one. One mobilization means one crew access window, one round of material deliveries, and one period of site disruption instead of two. A shaded pergola also changes how the turf beneath it performs and how the space gets used, which makes design decisions easier when both are planned together.
From a financing angle, bundling pushes you past any minimum project threshold a lender may apply, and it consolidates repayment into a single monthly payment instead of two. Ask for the bundled estimate and a phased estimate side by side, then compare the total cost of each path rather than the monthly payment alone.
Do Not Shrink the Base to Shrink the Loan
The most common way homeowners accidentally waste financed money is by cutting the base and drainage scope to bring the total down. On North Texas clay, a shallow or poorly compacted base shows up later as ripples, standing water, and seams that fail early. Replacing base work means paying for excavation twice.
If the number needs to come down, reduce square footage or simplify the pergola. Those cuts are recoverable later. Base depth is not something you can add without tearing the surface back out.

Match the Payment Term to the Life of the Upgrade
A sensible rule is that the repayment period should be shorter than the useful life of what you bought. Artificial turf installations from DFW Turf Pros carry a 25-year material warranty and a 5-year labor warranty with an annual maintenance visit, and a quality pergola is a long-horizon structure. Spreading a moderate balance across a term that stays comfortably inside those windows keeps you from still paying for a surface that has already been replaced.
Ways to Reduce the Amount You Finance
- Ask about volume discounts on larger turf installations, since per-square-foot pricing often improves with size
- Phase the project: turf and base first, pergola next season, using the first year to confirm how the space actually gets used
- Get a written estimate, using a planning calculator if one is available, so you are comparing real numbers instead of a verbal range
- Clear the balance inside the 0% window rather than accepting the minimum payment
Questions to Ask Before You Sign
- What is the exact promotional period, and is interest waived or deferred?
- What is the rate after the promo ends, and is it fixed?
- Are there origination, documentation, or prepayment fees?
- Does the financing run through the contractor or through a third-party lender?
- How are extra payments applied to the balance?
Get the answers in writing. A contractor who is comfortable with those questions is usually the same one who is comfortable showing you base depth and drainage detail before you commit to a number.
Frequently Asked Questions
Does 0% APR financing really cost nothing?
Only if you follow the terms exactly. Interest is typically waived or deferred for a set window, and if a balance remains when that window closes, a standard rate applies. Missed payments can also end the promotional rate early. Ask for the total cost assuming minimum payments, then compare it to the payoff plan you actually intend to follow.
Can I finance artificial turf and a pergola together?
Yes, and bundling is often the cleaner route. One application covers both scopes, one payment schedule replaces two, and the work gets sequenced properly so the pergola is not installed over fresh turf. Ask for a combined estimate and a phased estimate so you can compare total cost rather than monthly payment.
Is it better to pay cash or finance a backyard upgrade?
Cash is cheaper if using it does not drain your emergency reserves. Financing makes sense when the rate is genuinely low and the alternative is delaying the project for years or cutting base and drainage work to fit a smaller budget. The real test is whether the monthly payment fits comfortably alongside your other obligations.
What should I do if I want to pay the loan off early?
Confirm there is no prepayment penalty before you sign, then put extra money toward principal whenever you can. Clearing the balance before the promotional window closes is the single biggest protection against a deferred-interest surprise. Ask the lender directly how extra payments are applied to the balance.
Ready to see what your yard needs?
Get a straightforward estimate from DFW Turf Pros, with no pressure and no surprises.